Artiklen er baseret på følgende kilder: Goldman Sachs (Jan Hatzius, Jonathan Lightowler og Carly Davenport), Jefferies (Julien Dumoulin-Smith), Wells Fargo (Jerry Revich og Steve Tusa), Bank of America, Wolfe Research (Chris Senyek), GLJ Research (Gordon Johnson), SemiAnalysis, Bear Traps Report (Larry McDonald) og BloombergNEF (BNEF). Bloomberg, Associated Press (AP), NBC News (exitpolls), Polymarket, Cleanview, Baker Institute og ERCOT (Texas’ elnetoperatør).
Demokraternes overraskende valgsejr i Texas og flere andre amerikanske delstater kan blive en alvorlig bremse for de enorme investeringer i AI-datacentre. Ifølge Goldman Sachs ligger omkring 45 pct. af USA’s planlagte datacenterkapacitet i delstater, hvor nye demokratiske magthavere ventes at stramme reguleringen. Texas alene repræsenterer cirka 25-27 pct.
Den nye demokratiske guvernør i Texas, Gina Hinojosa, har lovet at fastholde et stop for nye datacenterprojekter, indtil der er vedtaget skrappere regler om strømforbrug, vandressourcer, miljø og skattefordele. Det kan tidligst ske i løbet af 2027.
Wells Fargo og Jefferies vurderer, at omkring 13 GW planlagt datacenterkapacitet i Texas er direkte eksponeret. Projekter uden de nødvendige myndighedstilladelser risikerer forsinkelser på 12-18 måneder, mens andre kan blive opgivet eller flyttet til mere erhvervsvenlige delstater.
Konsekvenserne kan række langt ud over selve datacenterbranchen. Wells Fargo vurderer, at en reduktion på 10 pct. af datacenterinvesteringerne i Texas isoleret vil reducere de samlede amerikanske AI-kapitalinvesteringer med 1,6 pct. En halvering af projekterne i Texas vil dermed kunne reducere de samlede AI-investeringer med omkring 8 pct.
Særligt producenter af elproduktionsudstyr, herunder Caterpillar og Cummins, kan blive ramt. Samtidig øger forsinkelserne finansieringsrisikoen i en sektor, hvor en betydelig del af investeringerne allerede er gældsfinansieret.
Goldman Sachs og Jefferies forventer overvejende, at investeringerne bliver udskudt frem for aflyst. Men analysens forfatter er væsentligt mere pessimistisk: Politisk modstand mod datacentre kan sprede sig til andre delstater og udvikle sig til en strukturel bremse for AI-boomet.
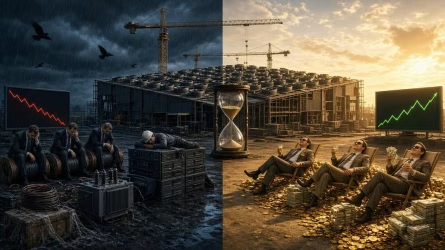
Den centrale konklusion: Den største risiko for AI-investeringerne er ikke længere kun mangel på strøm, udstyr og kapital. Politiske beslutninger om tilladelser og energipriser kan blive den afgørende flaskehals.
Orginal analyse:
Two days ago we laid out the states where Tuesday’s midterms could pull the plug on data centers. On Tuesday night, voters found the outlet.
In what Jefferies calls “the most impactful surprise” of a “blue tsunami”, Democrat Gina Hinojosa beat Greg Abbott roughly 52.8% to 45.7% (AP call at 11:17 PM ET) to become the first Democratic governor of Texas in more than three decades, on a platform whose centerpiece was an immediate moratorium on new data centers.
Recall that going into the vote, BofA noted “little evidence that equities reflect any probability of a change in the governor’s mansion,” and Polymarket gave Hinojosa just a 24.5% chance as of mid-October. Nasdaq futures did the math in real time:
Then, as we discussed earlier in “Texas Turns Blue, Futures Turn Green”, Wall Street did what it always does and bought the dip, with NQ ripping 929 points off the overnight lows. Which is fine for a morning (it won’t last). But the scoreboard matters far less than what the winners do with it, and in their first take on the results, Goldman’s chief economist Jan Hatzius and team skip the confetti and get straight to the part that matters for the AI trade:
“At the federal level, the outcome is less likely to change the outlook for data center and AI regulation, which would still need bipartisan support to pass the Senate and overcome a veto. However, Democratic wins at the state and local level are likely to lead to short-term data center moratoria, potentially affecting about 45% of planned US data center capacity expansion.”
In other words, Washington gets gridlock, and the AI buildout gets the state capitols. Which is exactly where BofA told us to look on Monday.
Almost Half The Pipeline Just Went Blue
Here is the damage, per Goldman’s “USA: Democrats Win a House and Senate Majority with Gains Well Above Expectations”: Republicans lost the governorships in Texas, Ohio, Nevada, Georgia and Michigan, while Democrats gained a trifecta in Pennsylvania and likely Arizona. In every one of those states except Ohio (where both candidates wanted a moratorium anyway), the Democratic side “explicitly campaigned on stricter data center regulation,” and Goldman expects new governors in Texas, Georgia and Michigan “to impose conditional moratoria pending new legislation restricting data centers.” That legislation could:
- end certain tax breaks (a priority for Hinojosa),
- tighten environmental, water and electricity rules, and
- make it easier for localities to impose their own moratoria.
And the number:
“The states where Democrats are likely to further restrict data centers account for roughly 45% of planned US data center capacity, with Texas alone accounting for roughly 25%.”
Add up Goldman’s own state shares (on a gigawatt basis, from Cleanview) and you actually get a little more than that:

Goldman’s pre-election exhibit shows just how much of a surprise the Texas result was: markets gave the stricter-regulation side only a 35% chance in the state that holds 26.7% of planned capacity, while the far less consequential Michigan was a 92% lock. Naturally, the one that flipped was the one that mattered.

Jefferies’ Julien Dumoulin-Smith, in “The Blue Morning After: State-by-State Election Scorecard” , shows that Texas was hardly alone: Democratic underdogs won up and down the Texas and Kansas ballots, with the Lt. Governor’s race (more on that in a moment) just as big an upset as the governor’s.

Jefferies’ key observation is that data centers are now “a bipartisan affordability issue“: candidates in both parties converged on cost-causer-pays in OH, GA, MI, WI, IA and TX, and data center-skeptic Democrats won governorships in TX, GA, OH, NV, MI, WI and IA. The bank expects “anti-data center efforts to continue across many state legislatures in 2027,” noting that Virginia moratorium bills are already advancing ahead of the January 13 session. Virginia, for those keeping score, is “Data Center Alley.” Here is the full governor scorecard:

Abbott Built The Freezer, Hinojosa Took The Handle Off
As regular readers know, Texas data centers were already on ice before a single vote was cast: on August 3 Abbott ordered the PUCT and ERCOT to audit every data center in the interconnection queue, and on September 21 he ordered TCEQ to halt all data center permits. The consensus hope was that a re-elected Abbott would quietly thaw the freezer after the audit. That hope died at 11:17 PM, the time of death of Republican ambitions in Texas.
Wells Fargo’s machinery analyst Jerry Revich explained why in “Texas Policy Reset Adds Timing Risk to 20-30% of the Data Center Power Pipeline”:
“Texas data center approvals have been frozen by executive directive since August, and the election converts that pause from one tied to an audit into one tied to legislation… ERCOT is targeting a December 10 audit filing, but that filing does not by itself reopen permitting. The governor-elect has said the pause should last until lawmakers act… The 90th Legislature convenes January 12 and its regular session ends May 31, 2027. SemiAnalysis estimates that a freeze lasting through the session would run about eight months from September, and that waiting for new rules could extend it close to a year, though a deal or special session could come sooner. In NBC’s exit polling, 75% of Texas voters opposed a new data center in their community.”
Translation: the audit was the exit door; Hinojosa just bricked it up until at least the end of May.

For those who haven’t followed the campaign, Bloomberg reminds us that Hinojosa called Abbott’s data center crackdown “nothing more than an election year stunt,” accused developers of “raising our utility rates and depleting our water,” and vowed to halt approvals until “a legislative session that puts Texans first.” Goldman’s Jonathan Lightowler confirms she “will not lift the freeze until more comprehensive regulation is passed,” a process that could push gigawatts slated for 2027 into 2028.
Jefferies has the most detailed read of what she actually wants:
- pause new data center permits and grid approvals (but not projects already under construction) until the Legislature acts;
- make large loads pay for the generation, transmission and interconnection they cause;
- phase out data center tax exemptions she says cost the state at least $1 billion a year;
- require disclosure of power and water needs; and
- direct the PUCT to freeze residential rates until large-load cost laws pass.
“Implementation detail is thin,” Jefferies notes dryly, “notably how a rate freeze would work alongside competitive retail pricing.” Well, maybe that’s a problem for 2027.
And here is the part the market has largely glossed over: the governor wasn’t even the biggest risk. Democrat Vikki Goodwin beat Dan Patrick for Lt. Governor (~52% to 46%), the first Democrat in that office in 27 years, and she too “supports pausing new data centers.” Since the Lt. Governor controls the Texas Senate’s legislative agenda, Jefferies had flagged her odds as “a potentially bigger under-appreciated risk” than the governor’s race: “that risk is now realized.” Add Talarico’s Senate win (he favors regulation over a moratorium) and Rosenthal becoming the first Democrat on the Railroad Commission in 32 years, and Jefferies’ verdict on Texas is blunt: “Not ‘business as usual.’”
Which is why, the night before, we were wondering about the paperwork:
How Much Of The AI Buildout Runs Through Austin? Between A Fifth And A Third
So how much is actually at stake? It depends on who you ask, and on whether you measure the cumulative pipeline or the near-term additions. Wells Fargo’s Steve Tusa puts Texas at ~81 GW, or ~20%, of the cumulative adjusted US pipeline, “more than twice Georgia or Virginia.” Goldman (via Cleanview) has it at 26.7% of planned capacity; the press-cited Wells Fargo figure Jefferies uses is ~27%. And SemiAnalysis has Texas adding close to 30% of all US gigawatts in 2028, which, as Revich points out, “is the window where power equipment orders sit today.”

“A few months of lost time in that market can move the national number,” SemiAnalysis warned before the vote. “The question now is how long the pause lasts.”
Of course, as we noted on Monday, a big chunk of that pipeline was always fantasy: ERCOT’s large-load queue hit ~474 GW in August, roughly 90% data centers and more than five times the grid’s all-time peak:

The near-term number is smaller but much more real. GLJ Research’s Gordon Johnson estimates roughly 13 GW of Texas data center capacity is “immediately exposed” by Hinojosa’s win (Bear Traps’ Larry McDonald, citing Jefferies, puts it at 13.3 GW), enough to power about 10 million homes. Johnson’s triage, via Bloomberg, is the single most useful framework we have seen today:
“Projects with power, permits and steel keep going,” while those with power but no state environmental permits slip 12 to 18 months. But those “projects with neither probably go to Louisiana, Oklahoma or nowhere.”
Louisiana, as it happens, just elected a 4-1 Republican PSC that Wells Fargo calls “the most constructive setup” for Entergy’s buildout. Funny how that works.
Wolfe’s Chris Senyek puts the Texas backlog in context: in raw count, Texas has roughly 1,000 announced data centers, almost double Virginia’s ~570 (chart source Wolfe Research):

And the bottom panel is why this matters: “despite moratoriums, bottlenecks, and general negative consumer sentiment around the AI Buildout, construction put in place for data centers has hit new highs and year-to-date surpasses 2025’s total dollar amount.” Senyek liked last night’s AMD and SMCI prints, but in his “Chart of the Day” he concedes that “the surprise victory by Hinojosa in Texas and subsequent ‘Blue Wave’ across Congress spells trouble for the AI trade in the very short-term,” adding that Texas “could likely serve as a model for opposition response to the buildout.”
That last bit is the real risk. The other 49 states are watching Austin.
Power Is Where The Delay Bites (Including Behind The Meter)
The gigawatts in the headlines are data center load, but the more immediate pain is in the equipment that powers them and here Wells Fargo’s Revich has done much of the granular work. Across the ~37 GW in WF’s reciprocating engine and CAT turbine trackers, about 3 GW of Caterpillar (CAT) and Cummins (CMI)-supplied capacity sits on Texas projects “now seemingly on hold”:
- Cummins’ entire 2.0 GW tracked prime position is its Circe Energy award for a behind-the-meter West Texas HPC campus, with deliveries scheduled through 2030;
- at least ~1.1 GW and ~$1.2 billion of CAT turbine content sits on Texas projects awaiting state action, led by Microsoft/Chevron’s Project Kilby and Stargate’s Abilene campus; and
- outside WF’s coverage, INNIO’s VoltaGrid orders add another 1.5 GW in Shackelford County.
“Several tracker entries are undisclosed, so these figures are floors,” Revich adds. Here is the list of named Texas projects stuck waiting for Austin, including our old friend Nexus Hubbard, the Anthropic campus whose $15 billion bridge loan the banks got stuck holding last week:

The mechanism is what makes this nasty: power gen lead times now extend into 2030, well past the ~18 months of visibility an air permit provides, so a 2029-30 OEM delivery slot is matched to a campus phase that may not yet hold its state permits. If the phase slips, the slot gets deferred or resequenced to another customer. And because Abbott’s September TCEQ directive reaches air permits, “on-site prime generation, the industry’s route around the grid queue, is now caught by the September directive as well.”
That one stings: having pounded the table since last December that “behind the meter” is the only sane way to power AI (a view Goldman has since come around to, now seeing behind-the-meter powering 25% of all data centers by 2030), we are watching Texas freeze precisely the projects that bring their own power plant. Even the escape hatch now needs a permit!
Then there is the money. Revich’s mea culpa is worth quoting in full:
“Our work centered on physical constraints — machinery supply, permits, interconnect queues, lead times — and we treated financing as available. That was the wrong assumption. Since September we have tracked CDS, which suggest rising risk.”
Welcome to the party: we have been warning since last October that the AI buildout runs on debt, and every month of permitting delay is another month of bridge loans that can’t be termed out (oh, and we have been tracking CDS since last November). Which brings us to the newest entry on our running casualty list:

The GDP Math: “That’s The Revenue Stream A Moratorium Starves”
Why should anyone outside of Houston utility land care? Bear Traps’ Larry McDonald did the arithmetic in his overnight recap and his focus is the rate of change rather than the overnight stock reaction:
“Texas is roughly 27% of planned US data center capacity through 2030 — Jefferies puts 13.3 GW of announced projects at risk. Baker Institute says Texas data center investment is $66B this year, on a baseline of $85B next year. Wells Fargo’s math: every 10% haircut to Texas data centers is a 1.6% hit to total AI capex, all else equal. AI-related investment already added 1.2% to recent US GDP growth, and the five biggest hyperscalers just spent $237B in a single quarter — 99% up year over year — with 2027 guided higher everywhere… If that capex curve flattens or rolls over because the single biggest build state just put a political chokehold on permitting, you’re looking at a direct GDP input shrinking at the exact moment hyperscaler free cash flow has already turned negative and debt is funding a third of the build. BNEF estimates AI capacity earns about one point seven six billion per gigawatt per month — that’s the revenue stream a moratorium starves. She takes office in January.”
Let’s extend the napkin math some more: if 1.6% of AI capex rides on every 10% of Texas, a 25% haircut is a ~4% hit, and if the panelists at Wells Fargo’s data center conference are right that “50%+ of Texas projects could be cancelled,” it’s ~8% of total AI capex, gone (all else equal):

On the revenue side, GLJ’s ~13 GW slipping 12-18 months at BNEF’s ~$1.76 billion per GW per month works out to something like $275-$410 billion of AI revenue pushed to the right. That assumes all of it is real capacity with real tenants, which, as the ERCOT queue shows, is a big assumption. Still, even a fraction of that is a lot of revenue for an industry already funding a third of its build with debt.
“Short-Term”… Famous Last Words
To be fair, the sellside is doing its best to end on a soothing note: here’s Goldman’s Hatzius:
“However, since data centers are low on the list of priorities for voters this election, we expect that the issue will fade somewhat in importance in the ensuing months and that these moratoria will not be long-lived if they are enacted.”
Goldman’s utilities analyst Carly Davenport sees Texas as “primarily a risk to the timing of development rather than the longer term opportunity,” and Jefferies’ headline is “Demand moves right, not away,” adding that “many early indications are for pragmatic new Democratic governors with potential announcements as soon as 1Q27 in select states.”
Maybe. But “short-term” is doing a lot of work in a sentence about a governor who has already said the freeze stays until new laws pass, a Lt. Governor who controls the Senate agenda and also wants a pause, a legislature that meets on a biennial calendar, a party that expressly campaigned on making it easier for localities to impose their own moratoria, and an electorate where 61% now strongly oppose a data center down the road. As for data centers being “low on the list of priorities,” only 7% of voters ranked them a top issue… but the issue they are blamed for, the electric bill, just flipped Texas. Temporary moratoria have a funny way of becoming permanent permitting regimes, and every month of delay lands on a buildout where the financing side is already cracking.
So which is it: a brief political pause the market can look through, or the moment the AI buildout’s biggest state turned off the tap? We lean toward the latter, at least through the end of the Texas session on May 31, 2027, and probably well past it for the projects that have neither power nor permits nor steel. We’ll tally the winners and losers, and the Texas copycats in Georgia, Ohio and Michigan, in a follow-up post later today.
For now, the winners look like the ones BofA flagged on Monday: projects that are already energized, and states that made data centers pay their own way and bring their own power before the voters forced them to. Everyone else just learned that the binding constraint on AI now sits in the governor’s mansion.
Here is what Wells Fargo says to watch between now and then; the first real read is ERCOT’s December 10 audit filing: