
Compute demand is significantly greater than supply, so the speed of the data center buildout matters.
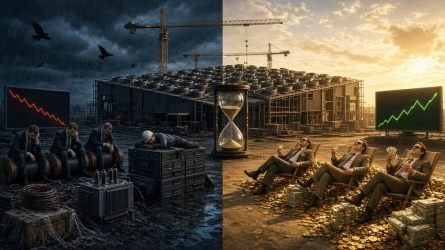
Who are the winners and losers if the buildout takes longer?
Winners
- Owners of operating data centers. Capacity that is already online can raise rents and fill every megawatt, since new competitors cannot arrive quickly.
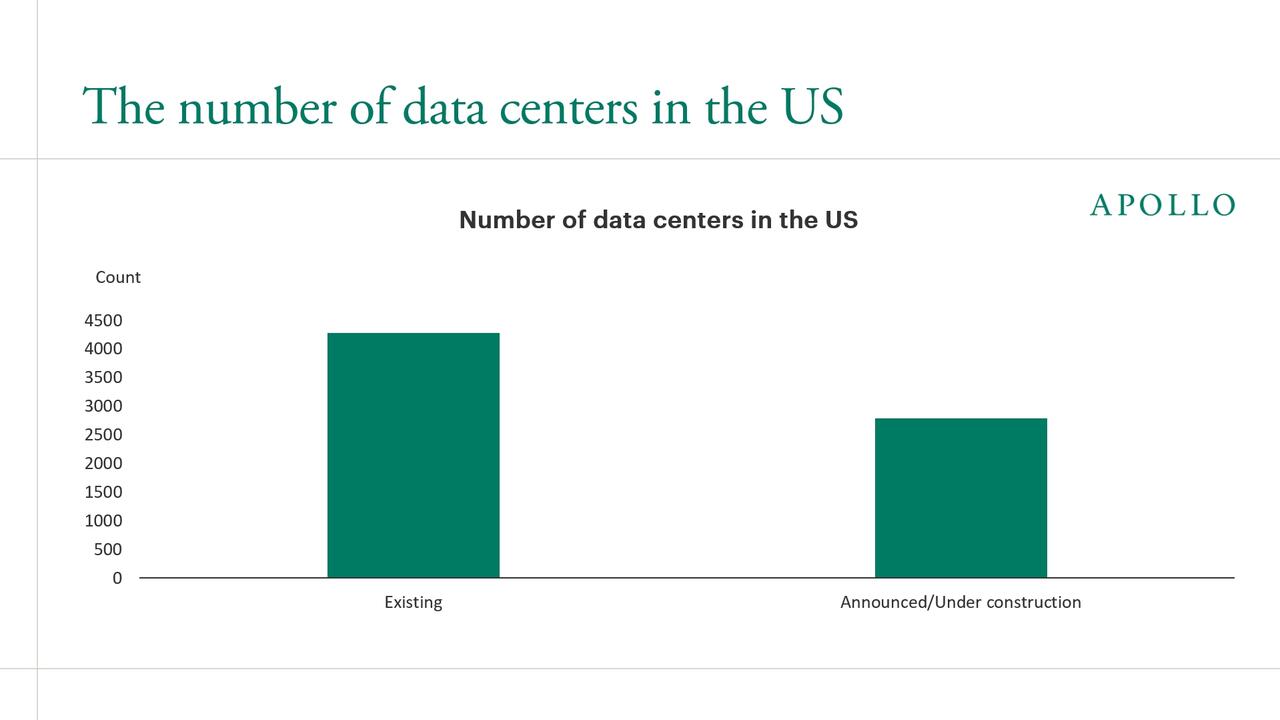
- Hyperscalers with capacity already secured. Those that locked in power, land and chips early can keep serving customers while rivals wait.
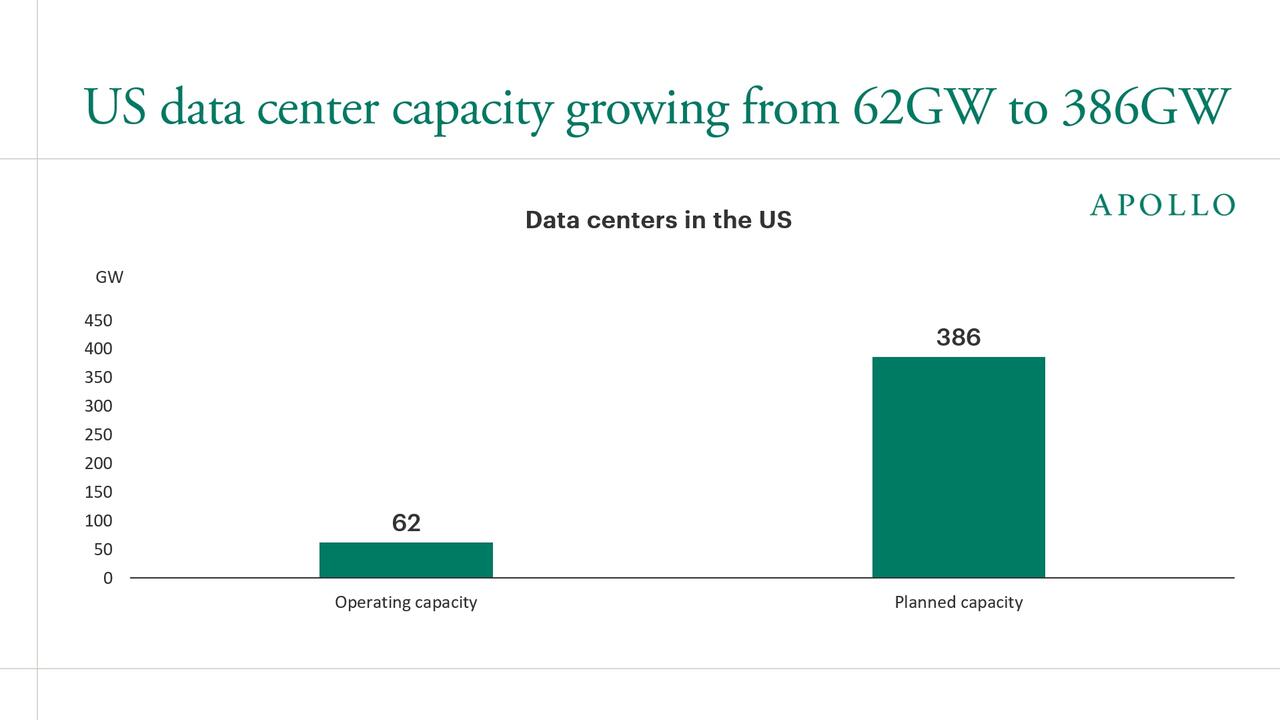
- Holders of powered land and grid access. Sites with secured power, interconnection and permits are the scarcest input and hardest to replicate, so their value rises.
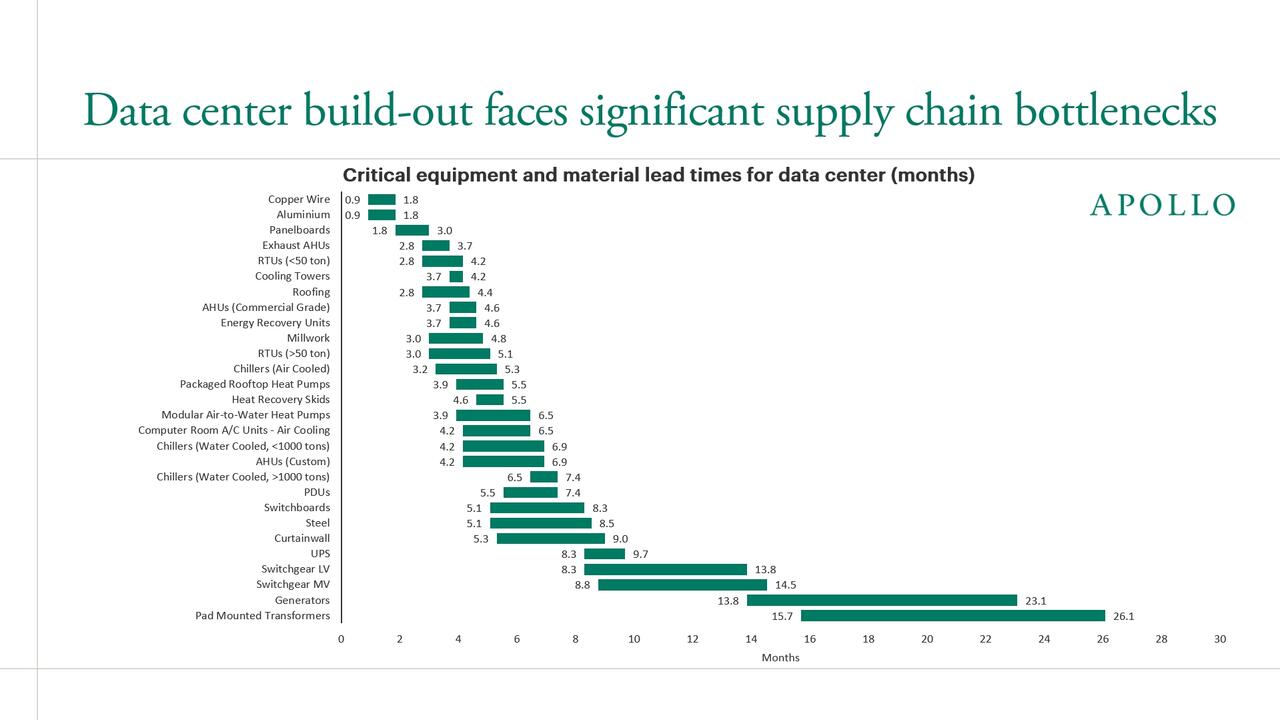
- Suppliers of long-lead equipment. Makers of transformers, switchgear, generators and cooling gear keep long backlogs and pricing power, with lead times of up to 26 months for transformers.
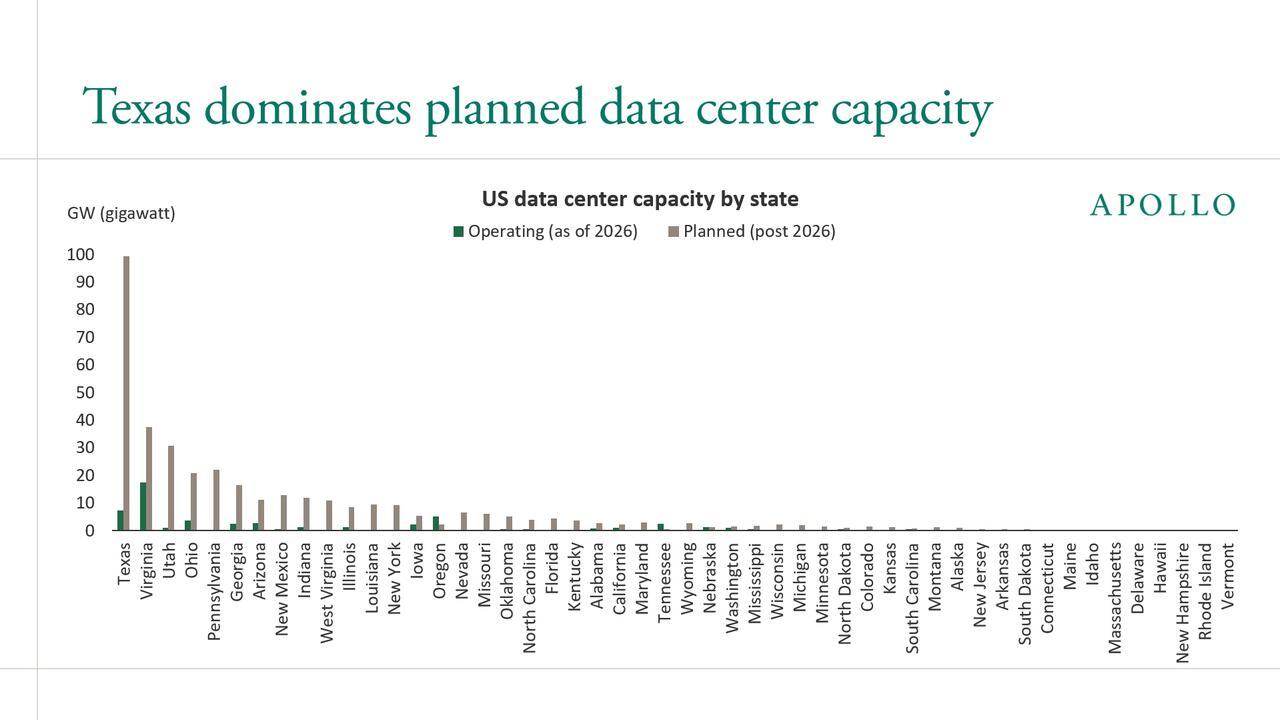
- Power producers and on-site generation. Where the grid is the bottleneck, gas turbines, fuel cells and batteries become more valuable.
Losers
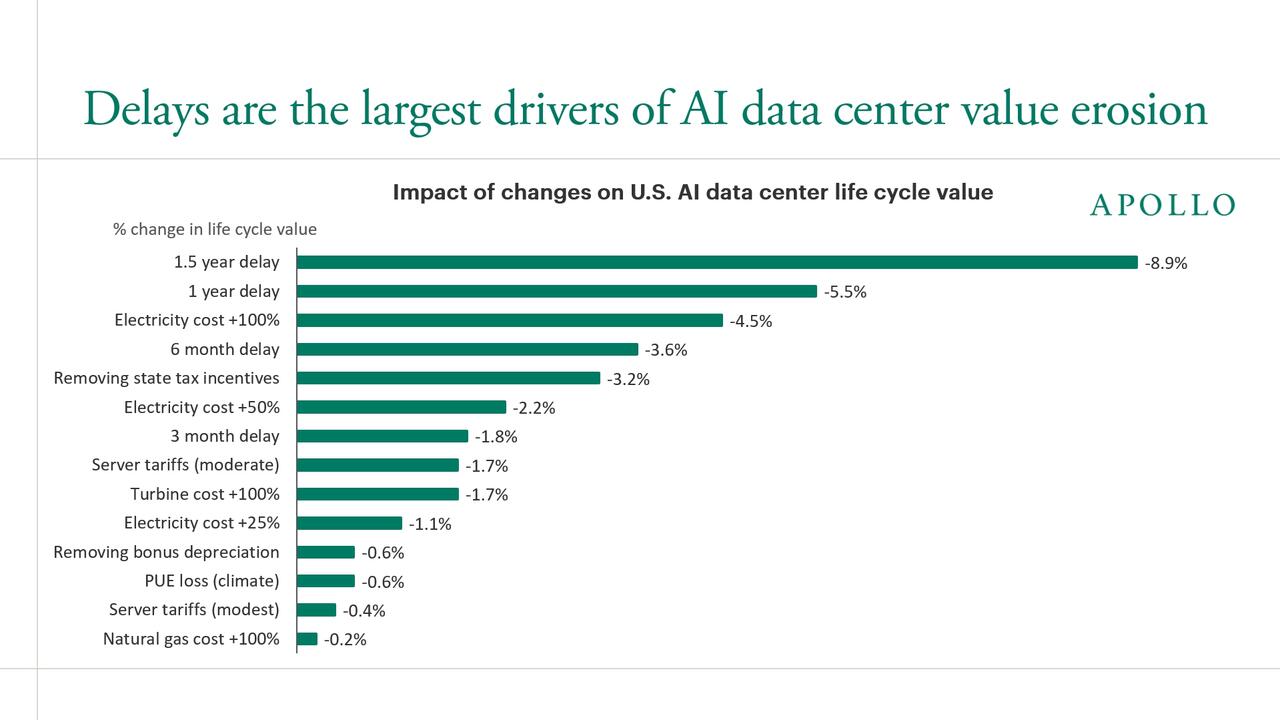
- Hyperscalers’ growth and earnings. Revenue is capped by supply rather than demand, and committed capex keeps accruing while capacity sits idle. Pricing power on existing capacity only partly offsets this, so earnings growth slows versus plan.
- AI labs, startups and enterprise buyers. They face rationing, higher prices and slower model training and product launches, with smaller players crowded out first.
- Developers and construction-stage investors. Cash flows start later while interest and carrying costs continue, lowering returns. Leveraged or pre-lease-dependent developers face covenant and refinancing stress.
- Equity investors in the AI trade. Valuations that assume on-time delivery are exposed to earnings revisions and multiple compression.
- The broader economy. Near-term GDP growth, which leans on AI investment, is lower, and the productivity gains from AI arrive later. Households and businesses on the same grid may also see higher electricity costs.
For chipmakers, the outcome of a delay is more mixed. Chip demand stays strong, but if sites cannot energize fast enough, chip deliveries could outrun installation and delay revenue.
The key distinction for investors is delay versus cancellation. A delay hurts returns by pushing cash flows out, but the asset remains and may become more valuable. The real risk is that scarcity unwinds, for example, if supply catches up in a rush or demand softens, which would erode the premium on existing capacity.
The bottom line for investors is that a delay would favor assets tied to scarce physical capacity, such as operating data centers, power producers and long-lead equipment makers, while assets priced on on-time delivery would underperform, notably AI-linked equities with high multiples and the debt of leveraged developers. Chipmakers face mainly timing risk, and hyperscaler bonds face mostly spread risk rather than default risk.