Resume af teksten:
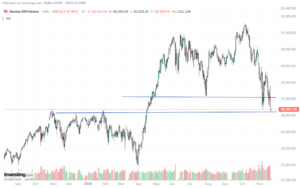
S&P 500-indekset er faldet 8,5 pct. fra årets højeste niveau efter endnu en dag med tab.
Korrektionen knyttes til udsigten til en hurtigere stramning af Federal Reserves pengepolitik.
Kerne-PCE for oktober offentliggøres næste onsdag og ventes at stige til 3,2 pct. på årsbasis.
Dollaren ventes at forblive stærk, mens carry-handler og valutaer i vækstøkonomier er under pres.
Brasiliens centralbank solgte 1 mia. dollar, men støtten til realen var kortvarig.
EUR/USD ligger fortsat under 1,10, mens den ungarske forint er under betydeligt pres.
Storbritannien og EU ventes at annoncere aftaler om grænsekontrol, emissionshandel og unges mobilitet.
USD/BRL steg igen efter interventionen, og USD/MXN handles over 19,00.
Fra ING:

After another day of losses, the US S&P 500 index is now 8.5% off its highs of the year. The extent of this correction is not far from that seen in March this year (9.5%) and way off the ‘Liberation Day’ rout of 21% seen in March/April 2025. The cause of the current correction has been the threat of a faster Federal Reserve tightening cycle, put on the table by the Fed’s Christopher Waller last week. We discussed high US real interest rates here yesterday . And the volatility in tech stocks may also be owing to this week’s Anthropic IPO, where investors have probably been shuffling portfolios to participate in a $100bn IPO. The fact that the Fed wants to tighten faster because of a demand shock should not necessarily be bad news for equities and, barring some major earning misses, the case for another 10% correction in equities is a weak one.
Yet there seems no reason for the Fed to drop its hawkish rhetoric anytime soon. Next Wednesday sees the release of the Fed’s preferred inflation measure – the core PCE index. The October data is expected to show the year-on-year rate rising to 3.2% with upside risks, and confirm that the Fed will need to take action.
For FX, that means a continued strong dollar and continued pressure on popular carry trades. The Latam complex has had a terrible week, with the most popular carry position, the Colombian peso, off heavily. Brazil yesterday stepped in with FX intervention, but $1bn in sales was quickly overwhelmed. Elsewhere, the big drop in metals has left the South African rand vulnerable, and a dovish central bank has seen an unwind of crowded positions in Hungary’s forint. We are also starting to see expectations build for rate cuts in Australia next year on the view that the Reserve Bank of Australia has overtightened. We highlighted this as one of the key risks in our 2027 FX Outlook . Pressure may also be building on long positions in the Turkish lira, where implied yields are starting to rise again.
A big carry trade unwind and emerging markets sell-off remain a positive for the dollar, and to a lesser degree, the yen. We expect the dollar to hold gains into next week and keep 104.60 as a near-term DXY target.
The US data calendar is light today, and the only Fed speakers are the hawkish Waller (10:15CET) and Lisa Cook, who surprisingly voted for a hike at the October FOMC meeting.
Chris Turner

EUR/USD continues to consolidate below 1.10. Our FX options traders suggest the low volatility price action here is a function of a lot of FX options barriers in the 1.0850-1.0950 area. Nonetheless, a correction in risk assets – and especially a correction in emerging market currencies – is typically dollar-positive, and we expect EUR/USD to face continuing downside risks. 1.0880 remains the potential for this move.
On the calendar is the release of eurozone negotiated wages for the third quarter. These are expected at 2.6% year-on-year, way off the 4-5% levels seen in 2024-2025 that would have worried the European Central Bank with the threat of second-round effects.
Elsewhere in Europe, the Hungarian forint is under heavy pressure. The National Bank of Hungary’s dovish tilt at this week’s meeting won’t have helped, but long forint positions would always have been vulnerable to a global carry trade unwind. So far, positions in the long end of the Hungarian local currency bond market have been untouched – this is where investors are positioned for Hungary’s euro story. Any sharp spike in these bond yields would caution a deeper correction to the Hungary story and even more pressure on the forint. Any EUR/HUF close above the 373.65 upside gap from April would warn of an extension to 380.
Chris Turner

At a press conference in Brussels today, UK Prime Minister Andy Burnham and EU leaders are expected to announce three new agreements. The first is on SPS (Sanitary and Phytosanitary measures), which will reduce border checks on trade in food, animals and plants. The second is on a greater alignment between the separate EU and UK Emissions Trading Schemes (ETS), where greater recognition of each other’s schemes can reduce carbon-related friction in trade – especially important for the steel and manufacturing sectors. The third looks at the thorny issue of mobility in the Youth Experience Scheme (YES), where up to 100,000 18-31 year-olds can obtain work visas for up to three years. Burnham will be marketing these deals as addressing the cost-of-living crisis and giving young Britons valuable opportunities overseas.
The deals, as always, will be subject to last-minute negotiation and serve as a reminder to the Burnham government that ‘cherry-picking’ the best parts of a relationship with the EU is no easy task. That may sway the Labour Party against any commitment to rejoin the EU in its next election manifesto – which could potentially emerge as early as next year.
Sterling typically responds well to the prospect of closer UK ties with Europe on the view that reversing a bad Brexit deal can generate a 1-2% larger UK economy in 5-10 years’ time. Today’s agreements are fully expected, however, and may not generate any independent sterling strength.
That said, we like sterling over the coming months on the view that Bank of England tightening expectations prove more resilient than those of the ECB. This corrective EUR/GBP rally may again stall in the 0.8400 area, and we are happy with a year-end forecast of 0.8300.
Chris Turner
USD/BRL briefly corrected yesterday when the Central Bank of Brazil announced it would conduct an auction to sell US$1 billion. Gains in the Brazilian real were only fleeting, with investors still wary that President Luiz Inácio Lula da Silva has no interest in fiscal consolidation. Back in late 2024, BCB had to increase the size of its spot USD auction to $3-5bn to provide stability to the real. We cannot rule out USD/BRL extending to the 6.00/6.30 region again, but imagine investors would start to find those levels as attractive again for the real and its high real interest rates.
Elsewhere, USD/MXN is trading comfortably through 19.00. This outcome cannot have been unexpected for Banxico after it cut rates in November. 19.60 is now the risk, assuming the dollar stays strong.
Chris Turner
Kilde: ING, https://think.ing.com/articles/national-bank-of-hungary-review-the-doves-arent-gone-yet/
Hurtige nyheder er stadig i beta-fasen, og fejl kan derfor forekomme.