Resume af teksten:
Energiforsyningen gennem Hormuzstrædet og Saudi-Arabiens øst-vest-pipeline ventes at være begrænset de kommende måneder.
Olie- og produkteksporten ventes at svinge mellem 9 og 14 millioner tønder dagligt mod cirka 22 millioner før konflikten.
Inflationsprognoserne løftes som følge af højere og mere vedvarende energipriser.
Inflationen i eurozonen ventes at toppe nær 4 procent senere i år og tidligt næste år.
Inflationen i eurozonen ventes først at nå målet i fjerde kvartal 2027.
Den økonomiske vækst ventes at være robust på kort sigt, men at aftage næste år.
ECB ventes at hæve indlånsrenten med yderligere 50 basispoint til 3 procent inden årets udgang.
Federal Reserve ventes at hæve renten med 50 basispoint til en øvre grænse på 4,25 procent.
Rentekut fra begge centralbanker kan blive aktuelle omkring udgangen af næste år.
Obligationsrenterne ventes først at stige og derefter falde, mens rentekurverne ventes at blive stejlere.
Fra ABN-Amro:
The recent escalation in the Middle East likely means higher for longer energy prices, inflation and interest rates. Energy supply through both Hormuz and the Saudi East-West pipeline is likely to remain constrained in the coming months. The higher profile for energy prices leads to an upward revision to our inflation forecasts, with a longer period of above-target rates. Economic growth remains resilient near term; will be dampened next year on higher energy prices, interest rates and slower AI capex growth. Faced with a longer period of above-target inflation, central banks are likely to move monetary policy into moderately restrictive territory. We expect 50bp of rate hikes from both the Fed and the ECB before year end, while the door could open for rate cuts by the end of next year. Bond yields are seen heading lower over our horizon as there are more hikes priced in than we expect in our new base case. Rising term premia should drive curve steepening.
Nick Kounis
Chief Economist
Bill Diviney
Head Macro Research / senior economist eurozone
The recent escalation in the Middle East likely means higher for longer energy prices, inflation and interest rates. A deal to fully re-open the Strait of Hormuz does not seem likely any time soon, whereas the likelihood of ongoing sporadic military clashes could also curtail the energy flows through the Strait. At the same time, the impact of attacks on Saudi energy infrastructure could also negatively impact pipeline exports. Against this background we are updating our base case.
In our previous scenario we assumed that we would see a more rapid normalisation of energy supply, with the supply deficit closing by the end of this year and a supply surplus building during the course of next year. This would have led to a significant fall in energy prices next year, with headline inflation falling rapidly. An agreement between the US and Iran is increasingly unlikely as both sides look to be digging in their heels and preparing for a longer stand off. At the same time, we had been seeing a pickup in energy flows through the Strait of Hormuz even without the deal. However, those flows have been recently constrained by military conflict between the US and Iran. In addition, new fronts in the conflict have opened up between the Houthis in Yemen, Iran-linked Shia militias in Iraq, and Saudi Arabia. Attacks in the Bab el-Mandeb choke point and around the port of Yanbu are hampering pipeline exports, which have been an important offset to Hormuz flows. Indeed, at the time of writing, the Saudi authorities have closed the East-West pipeline as a ‘precautionary measure’.
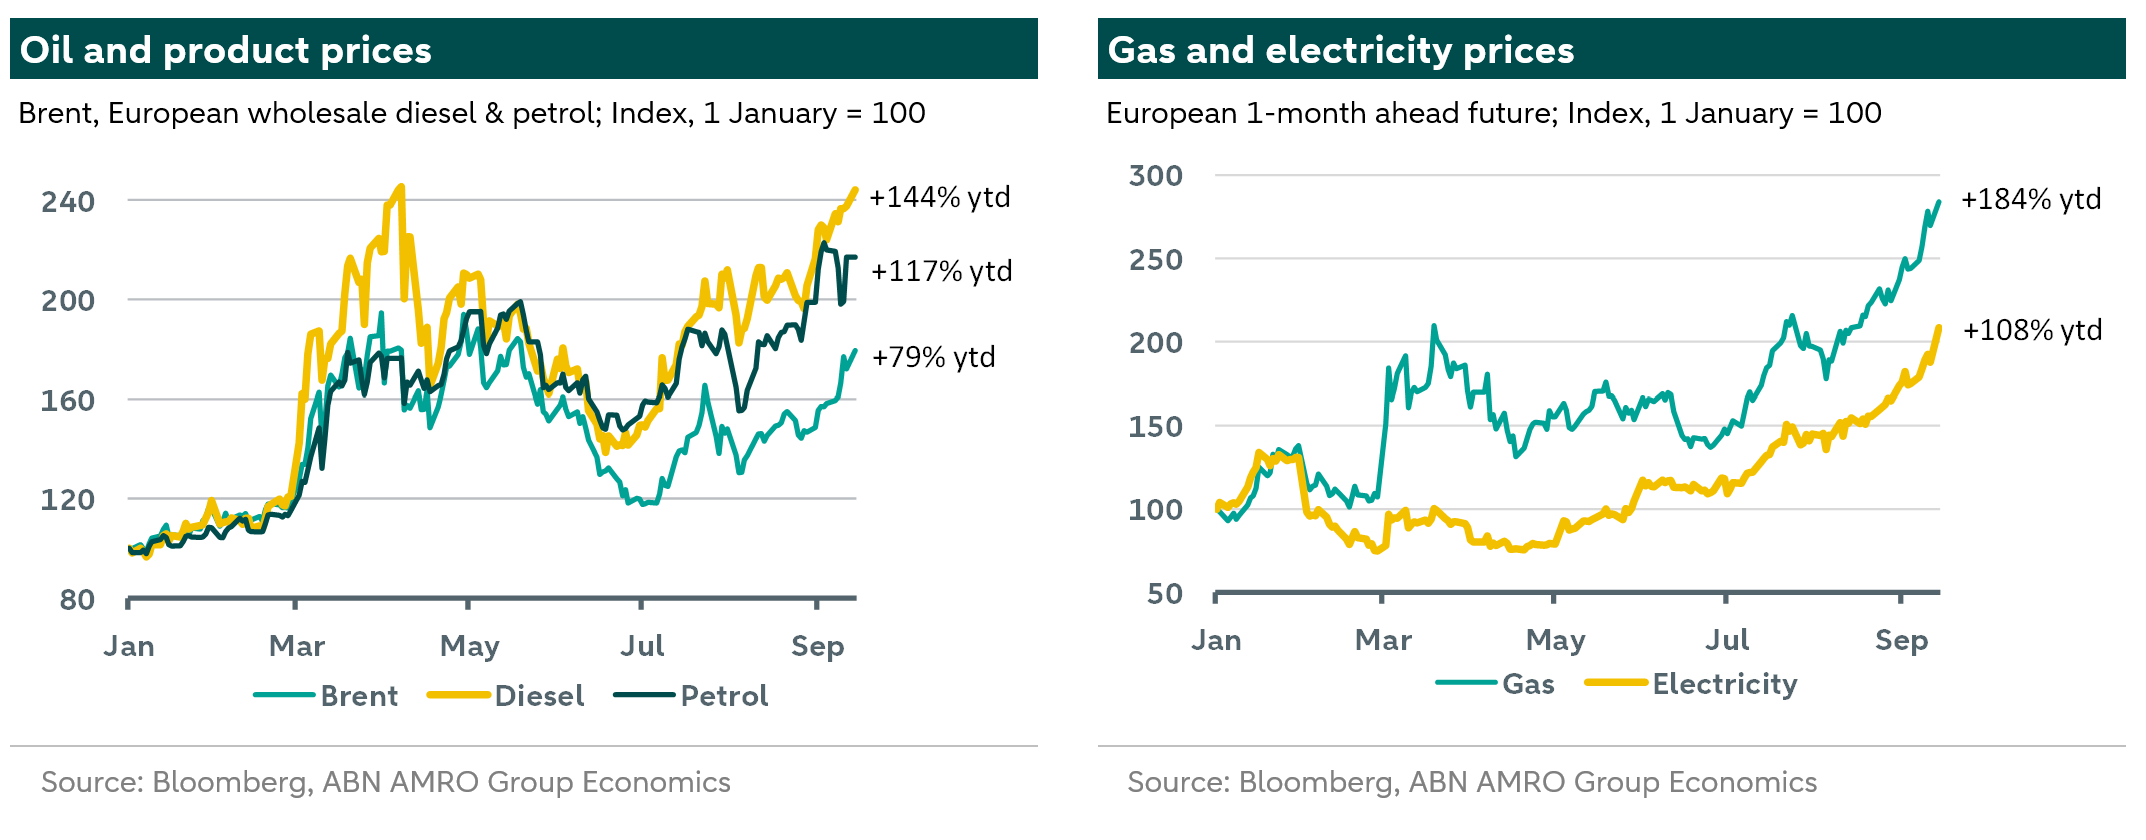
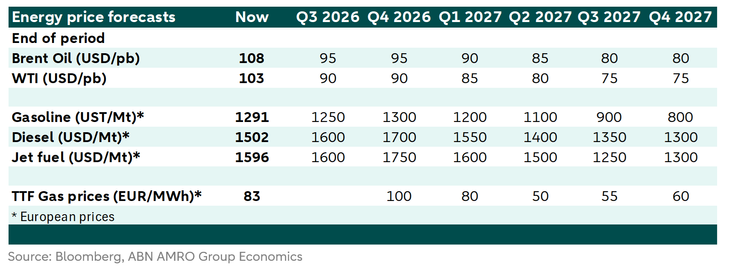
Our updated scenario is based on the judgement that there will be no US-Iran agreement for the foreseeable future. Through to the end Q1/Q2 next year we assume that exports from both Hormuz and through Yanbu are constrained by ongoing military tensions, albeit more sporadically than earlier in the conflict. This should keep oil and product exports oscillating between 9 and 14 mbd compared to around 22 mbd before the conflict started. Refinery capacity has been heavily impacted, and may see further reductions, also because of the Ukraine/Russia front. We assume that from around the middle of next year we will see a gradual rise in energy exports to more normal levels. Our view does not hinge on a US-Iran agreement, but a more stable environment could see dark traffic accelerating. At the same time, demand destruction and adaptation could also help return the market to better balance. In the case of European gas markets, low storage levels, tight market conditions, and intensified competition between Europe and Asia for US LNG cargoes will continue to put updated pressure on prices. Additional US LNG capacity coming online by the end of 2026 and during the first half of 2027 should provide significant market relief. Our updated energy price forecasts are set out in the table below.
The higher profile for energy prices leads to an upward revision to our inflation forecasts. This is both because of the direct effects and additional second round effects. In the eurozone, we now expect inflation to peak near 4% later this year and early next year, and stays higher for longer, with a return to target not foreseen until Q4 2027. This protracted period raises the risks of inflation broadening further, although we still do not expect a 2022-23 style wage-price spiral to take hold. All told, after an expected 3% reading for 2026, we raise our 2027 eurozone inflation forecast by 0.5pp to 2.7%. On the US side, our updated forecasts reflect both the upward revision in inflation as well as an initial attempt at incorporating the anticipated changes to the PCE methodology which is expected to reduce the y/y PCE inflation figure by 0.2pp. This leads to a marginal net increase in our forecasts for the remainder of the year, while next year’s path lies somewhat lower. It will reach a trough in 2027Q2 due to base effects from the Iran war, before slightly increasing to remain above target for the year.
The impact on economic growth of our new base case is moderate in the near term, but economic growth starts to lose some pace next year. One of our core convictions since energy prices started to spike is that it is a much bigger deal for inflation than economic growth and hence central banks would tilt hawkish. This is because the price shock was expected to not be that large or persistent from a historical perspective, while the energy intensity of economies had come down over the years. In addition, enormous AI capex and its spillovers to world trade would tend to overshadow the impact of the energy price shock, while both financial conditions and fiscal policy are still accommodative.
While we maintain this general view, the constellation of shocks does mean economic growth will be lower than we previously expected next year. First of all the energy price shock is expected to be larger and more persistent, while refined oil prices as well as gas prices (which of course what matters for consumers and businesses) are more elevated than crude. Second, interest rates are now also expected to be higher for longer, as explained in more detail below. Finally, AI capex growth could well lose some pace next year, not necessarily because of higher rates, but simply because it was extraordinarily high this year. Although the planned level of AI-related capex is expected to be higher next year than this year, the pace of increase will unlikely match the change between 2025 and 2026, when it more than doubled. Our updated macro forecasts are set out in the table at the end of this publication.
The risks to our inflation and growth forecasts are tilted to the upside and downside, respectively. This reflects that energy prices could be even higher for longer given the escalating situation in the Middle East. This would also mean even higher interest rates. Up to now, higher bond yields have not led to a significant tightening in financial conditions, but this is clearly a possibility. Especially if investor worries about a series of economies with weak fiscal positions (US, France, UK and Japan for instance) were to escalate even much further than currently expected.
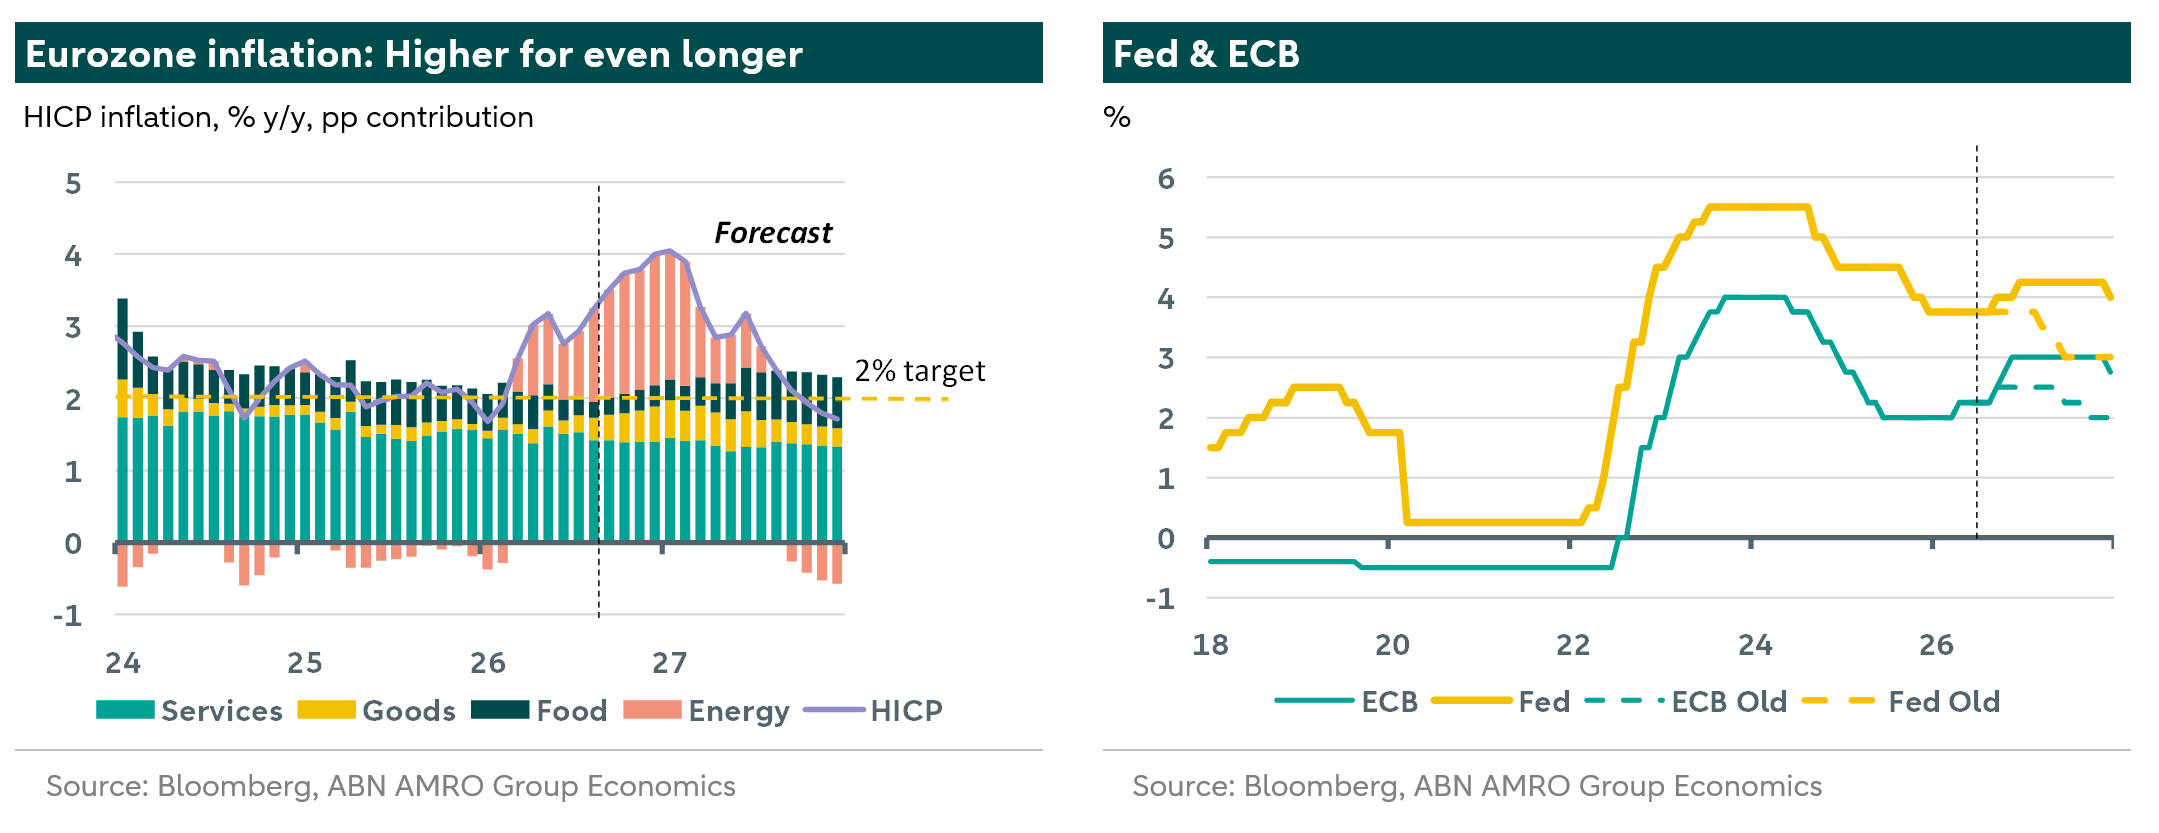
Faced with an even longer period of above-target inflation, central banks are likely to move monetary policy into moderately restrictive territory. There has not been much sign that the current level of policy rates is restrictive in the US and eurozone, despite the fact that the level in both cases is currently above those generally judged to be neutral. This might be because we are living through a historical troika of capex booms (AI, clean energy and defence). The ECB has of course already raised interest rates by 50bp, but its recent projections suggest that it is far from done. We now expect additional 25bp hikes in both October and December, taking the deposit rate to 3%. The Fed has so far been more reluctant to raise interest rates, with the majority of voting FOMC members taking the view that they were happy to hold as long as the trend of disinflation continued. However, the hotter than expected August CPI number, taken together with the likelihood of higher for longer energy prices, means the centre of gravity of the committee will likely shift ( see here ). We now expect a 25bp hike at this week’s meeting to be following by additional hike in December, taking the upper bound of the target for the Fed fund’s rate to 4.25%. Looking further ahead, we think both for the ECB and the Fed, the combination of falling inflation and moderate economic growth will open the door for rate cuts around the end of next year.
The higher profile of our projection for central bank policy rates means we have also revised our forecasts for bond yields higher. Compared to current bond yield levels, we expect some further upward pressure in the near term, as central banks are expected to deliver 50bp in tightening before end-2026. However, yields decline during the rest of our forecast horizon because we expect the eventual peak in rates to be lower than markets are currently pricing, while at the end of the horizon we expect markets to start pricing in rate cuts. For longer maturities, the impact of unwinding rate hike expectations will be offset by higher term premia. This remains a long-standing pillar of our bond market views. Ongoing higher bond supply and the deterioration of public finances globally have not yet been fully reflected in bond yields. As a result, we expect curves to steepen during our horizon. Meanwhile, we expect the euro to be range-bound against the dollar over the next few months, as interest rate differentials will no longer be a factor driving the euro higher (we previously expected the Fed to remain on hold). Towards the end of the horizon, as we think investors will increasingly focus on the poor US fiscal situation, severe external imbalances, as well as some re-appraisal of US economic strength. Our updated forecasts are set out in the table above.
Nick Kounis
Chief Economist
Bill Diviney
Head Macro Research / senior economist eurozone
Kilde: ABN-Amro, https://www.abnamro.com/research/en/our-research/updating-our-scenario-higher-for-longer
Hurtige nyheder er stadig i beta-fasen, og fejl kan derfor forekomme.